Kuwaitisation and Restructuring Risks Drive Banks to Tighten Job Stability Checks.
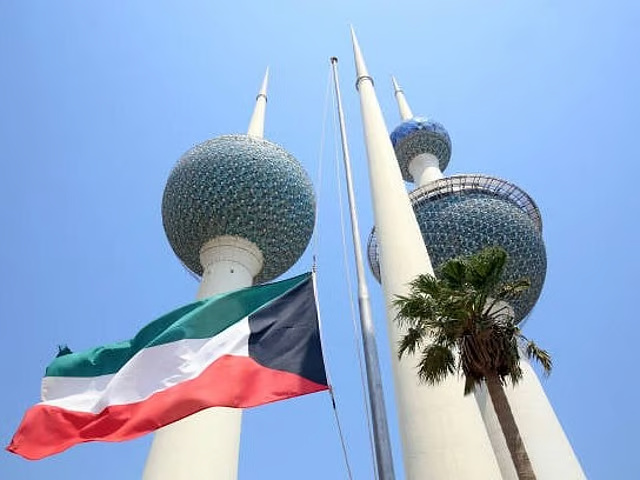
Dubai: Banks in Kuwait are adopting stricter lending criteria for expatriates as concerns over employment stability, Kuwaitisation policies and the possibility of contract terminations lead lenders to take a more cautious approach to extending credit, according to banking sector sources.
The tighter scrutiny does not represent a halt in lending to expatriates. Instead, banks are placing greater emphasis on borrowers’ employment prospects and assessing whether their jobs are likely to remain secure throughout the loan repayment period.
Banks are placing greater scrutiny on government positions affected by Kuwaitisation, roles considered surplus to staffing requirements and occupations undergoing restructuring.
The increased checks extend to some government school teachers working in specialisations affected by surplus staffing plans, as well as employees of cooperative societies and public benefit organisations.
Banks continue to extend credit to expatriates working in professions considered relatively stable, including doctors, engineers, healthcare professionals, technicians and employees in the technology and artificial intelligence sectors. Teachers in specialisations that are not considered at risk from Kuwaitisation measures also remain eligible for lending.
Lenders are also placing greater emphasis on factors such as length of service, salary levels, credit history and end-of-service benefits when assessing applications. Employees with around 10 years or more of service may be considered lower-risk borrowers, as accumulated end-of-service benefits can provide an additional layer of financial security.
Newly appointed expatriates and employees with lower educational qualifications are facing stricter lending conditions, which could include reduced credit limits as banks adopt a more cautious approach to assessing repayment risks.
Eligible Kuwaiti and expatriate borrowers can obtain combined consumer and housing financing of up to KD95,000, subject to regulatory requirements and individual bank policies. Financing of KD95,000 would require a monthly salary of about KD2,750, with an estimated instalment of KD1,100, equivalent to 40 per cent of net salary. For a KD25,000 loan, borrowers would need a salary of approximately KD1,225, with an estimated monthly repayment of KD490.
Banks are also paying closer attention to the financial strength and reputation of employers, as well as their record of paying salaries on time. Employees working for companies listed on Boursa Kuwait or organisations already approved by a lender may receive more favourable consideration.
Expected Kuwaitisation measures are also affecting the length of repayment periods offered to some borrowers. Judges continue to maintain strong credit profiles, but plans to Kuwaitise the judiciary by the end of 2030 could lead banks to align loan repayment terms with the anticipated replacement timeline.
High-value expatriate customers with significant deposits, assets or accumulated end-of-service benefits continue to receive preferential consideration from banks. Depending on their financial profile, these customers may qualify for higher financing limits and more competitive lending rates.