Understanding Taxes on Share Sales, Current Regulations and How a Potential Repeal Could Impact Investors.
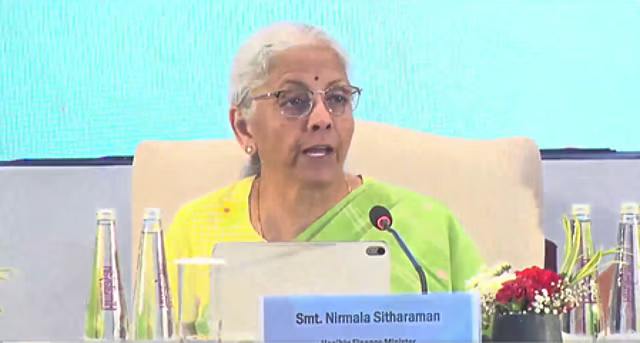
Dubai: Indian expatriates residing in the UAE could potentially retain a larger share of their earnings from investments in Indian stocks if the Indian government decides to lower investment-related taxes, following Finance Minister Nirmala Sitharaman’s indication that she is open to considering investors’ concerns.
Her comments have fuelled expectations of a possible review of investment taxes ahead of the February Budget. Indian equity markets responded positively on Tuesday, with the Nifty 50 index gaining 1.6% at the close, marking its strongest single-day rise in over two months, according to Bloomberg.
Speaking at the Bloomberg New Economy Forum in New Delhi, Sitharaman welcomed discussions surrounding the issue and expressed her willingness to listen to investors’ views and concerns.
Although Finance Minister Nirmala Sitharaman did not commit to reducing or eliminating the Securities Transaction Tax (STT) or Long-Term Capital Gains (LTCG) tax, understanding the distinction between these two levies is particularly important for Non-Resident Indians (NRIs).
Securities Transaction Tax is imposed on certain investment transactions, including the purchase and sale of eligible securities, while Long-Term Capital Gains tax applies to taxable profits earned from selling investments held beyond the prescribed period. Eliminating or lowering either tax could ease investors’ financial burden, although the potential savings would differ depending on the type of tax revised.
Why Investors Reacted Positively
Indian stock market investors responded favourably to indications that the government might reconsider taxes affecting investment returns. Sitharaman’s remarks kept the possibility of tax reforms open, although she refrained from announcing any concrete measures ahead of the upcoming Budget.
The market’s upward movement was partly driven by expectations of potential tax relief. However, no official decision regarding tax reductions had been made, and other factors, including strong performances by technology stocks, also contributed to the rally.
Separately, SBI Research has recommended abolishing taxes on long-term equity capital gains, provided investors maintain their holdings for a minimum period of two or three years. However, this proposal remains a research recommendation and has not been adopted as official government policy.
Understanding Taxes on Share Transactions
Securities Transaction Tax (STT) is levied on certain purchases and sales of securities in India. For regular delivery-based transactions involving listed Indian shares held in a demat account, the applicable STT rate is 0.1% on both the purchase and sale value.
For example, purchasing shares worth Rs1,000,000 would result in an STT charge of Rs1,000. If those shares are subsequently sold for Rs1,500,000, an additional Rs1,500 would be payable. The combined STT liability would therefore amount to Rs2,500, excluding brokerage fees and other transaction expenses.
Importantly, STT is charged regardless of whether an investor makes a profit or incurs a loss. If the same shares are sold for Rs800,000 instead, the investor would still pay Rs800 in STT on the sale.
Capital gains tax operates differently, as it is calculated on taxable profits realised when investments are sold or redeemed. An increase in the market value of shares does not, by itself, create a capital gains tax liability while the investment remains unsold.
How Capital Gains on Investments Are Taxed
For eligible listed equity shares and equity-oriented mutual funds, investments held for more than 12 months are generally classified as long-term holdings. Investments sold within 12 months of acquisition are typically treated as short-term.
Under the stated tax rules, qualifying short-term capital gains are subject to a base tax rate of 20%, while eligible long-term capital gains are taxed at 12.5% on the portion of annual gains exceeding Rs125,000.
The Rs125,000 exemption threshold applies to the investor’s total eligible long-term capital gains during the financial year, rather than separately to each investment, transaction or mutual fund.
Additionally, a 4% health and education cess is imposed on the calculated income tax, while applicable surcharges may further increase the overall tax liability.
For illustration, consider an investor who purchases shares for Rs1,000,000 and sells them for Rs1,500,000 after holding them for more than 12 months. This transaction generates a capital gain of Rs500,000.
Assuming this represents the investor’s only eligible long-term capital gain during the financial year, with no capital losses or other adjustments, the taxable gain would be calculated after applying the annual Rs125,000 exemption threshold.
After deducting the Rs125,000 annual exemption, the taxable long-term capital gain amounts to Rs375,000. Applying the 12.5% tax rate results in a base tax liability of Rs46,875. With the additional 4% health and education cess, and assuming no surcharge applies, the total capital gains tax payable reaches Rs48,750.
This amount is separate from the Rs2,500 paid in Securities Transaction Tax (STT) during the purchase and sale of the shares. The calculation does not include brokerage fees or other transaction-related expenses.
Why Investors Are Calling for Tax Relief
Investors have raised concerns about the combined financial impact of Securities Transaction Tax and capital gains tax, arguing that paying taxes on both transactions and investment profits reduces their overall returns.
According to a Bloomberg report, Nilesh Shah, Managing Director of Kotak Mahindra Asset Management Company, highlighted the additional financial burden created by the simultaneous application of these two taxes.
“This dual taxation has been a concern for investors, and we need to find the right balance,” Shah stated.
Although the two taxes are calculated differently, both affect investors’ overall returns. Securities Transaction Tax (STT) is charged on the total value of eligible securities transactions, whereas capital gains tax is imposed on taxable profits realised from selling investments. Together, these levies reduce the amount investors ultimately retain.
SBI Research has suggested that eliminating long-term capital gains tax while introducing an extended minimum holding period could encourage greater investment participation. For Non-Resident Indians (NRIs), such a measure could potentially reduce tax liabilities, provided they maintain their investments for the required duration.
However, investors who need to liquidate their holdings before completing the proposed holding period might not qualify for the benefit. Any potential savings would ultimately depend on the specific provisions introduced by the government.
How Tax Changes Affect Older Investments
India introduced Securities Transaction Tax in 2004. Before the taxation changes implemented in 2018, qualifying long-term capital gains from eligible equity investments were generally exempt from capital gains tax, although STT continued to apply.
In 2018, the government introduced a 10% tax on eligible long-term equity gains exceeding Rs100,000 annually. Subsequently, for transfers taking place on or after July 23, 2024, the long-term capital gains tax rate increased to 12.5%, while the annual exemption threshold was raised to Rs125,000. The applicable short-term capital gains tax rate also increased from 15% to 20%.
Investors should understand that purchasing shares before a tax rate increase does not necessarily guarantee taxation under the previous rate. Generally, the tax provisions in force when the investment is sold determine the applicable liability, subject to any specific exemptions or transitional protections.
For eligible investments acquired before February 1, 2018, India’s tax regulations provide grandfathering protection for certain gains accumulated before the introduction of long-term capital gains taxation. Under these provisions, the market value as of January 31, 2018 is considered when determining the deemed acquisition cost for tax calculations, subject to prescribed conditions.
However, this grandfathering provision does not exempt all profits earned after the specified date from taxation. Investors holding older shares must maintain accurate purchase records and obtain the relevant historical market values to determine their taxable capital gains correctly.
How Much Could Investors Save if Taxes Are Abolished?
Using the earlier investment example, eliminating Securities Transaction Tax (STT) before a future share sale could save an investor Rs1,500 on the selling transaction. However, capital gains tax would continue to apply unless the government separately revised or abolished it.
Similarly, if long-term capital gains tax were removed for the same qualifying transaction, the investor could save the illustrated Rs48,750 tax liability. STT would still be payable unless changes were also introduced to that levy.
For investments purchased before any potential STT abolition, the tax already paid at the time of purchase would not automatically be refunded. Likewise, eliminating capital gains tax would not necessarily result in refunds for taxes paid on previously completed share sales.
Investors who continue to hold their shares could potentially benefit from revised tax provisions when they eventually sell their investments. However, the government would first need to clarify the effective date of any changes, the categories of investments eligible for relief and whether additional conditions, such as an extended holding period, would apply.
No retrospective tax relief has been announced. Until new legislation is introduced and takes effect, the existing taxation framework remains applicable.
How Mutual Fund Taxation Differs from Shares
Equity-oriented mutual funds are subject to a different Securities Transaction Tax structure compared with direct equity investments.
Unlike regular delivery-based purchases of listed shares, which attract STT at 0.1%, purchases of equity-oriented mutual fund units generally do not incur the same transaction tax.
However, when investors sell or redeem eligible equity-oriented mutual fund units, STT is generally charged at a significantly lower rate of 0.001% of the transaction value.
For instance, redeeming equity-oriented mutual fund units worth Rs1,500,000 would attract Securities Transaction Tax (STT) of just Rs15. However, investors earning substantial long-term capital gains could face a considerably higher tax liability on their profits compared with the relatively small transaction tax.
Investors contributing regularly through a Systematic Investment Plan (SIP) should also understand that each instalment is treated as a separate investment with its own acquisition date. Consequently, a single redemption may involve both short-term and long-term capital gains, depending on how long the respective units have been held.
Any proposed tax reforms would need to clearly establish whether equity-oriented mutual funds would receive the same benefits as direct investments in listed shares. Investors should not automatically assume that tax relief proposed for equities would extend to every category of mutual fund.
Key Tax Considerations for UAE-Based NRIs
Indian expatriates residing in the UAE should understand that living outside India does not automatically exempt income or profits generated from Indian investments from Indian taxation. The applicable tax treatment depends on an individual’s Indian tax residency status, the nature of the investment and relevant tax regulations.
Non-Resident Indians are generally eligible for the Rs125,000 annual exemption on qualifying long-term equity capital gains. However, unlike eligible resident individuals, NRIs cannot adjust these gains against any unused portion of the basic income-tax exemption limit under the relevant provisions.
Additionally, mutual fund redemptions by NRIs may be subject to Tax Deducted at Source (TDS), meaning a portion of the proceeds can be withheld before the investor receives the funds. This deduction is treated as an advance payment towards the investor’s final tax liability rather than a separate additional tax imposed alongside STT and capital gains tax.
For UAE-based investors, any future reduction in investment-related taxes could increase the amount of money retained after selling shares or redeeming mutual fund units. Nevertheless, fluctuations in stock market valuations and movements in the Indian rupee against the UAE dirham would continue to influence the actual value of investment proceeds available for spending or reinvestment.
The ongoing discussion surrounding potential tax reforms ahead of India’s Budget raises important questions for NRIs with existing investments. Investors will be particularly interested in whether any proposed relief would apply to future sales of shares already held and whether an extended minimum holding period would be required to qualify.
Although Finance Minister Nirmala Sitharaman has indicated a willingness to consider investors’ concerns, no definitive changes have been announced. The eligibility requirements, implementation timelines and potential financial benefits will remain uncertain until the government provides further clarification.