Dubai market surges 3.95% and Hang Seng gains 3.3%, while Kospi falls 5.2% amid regulatory concerns.
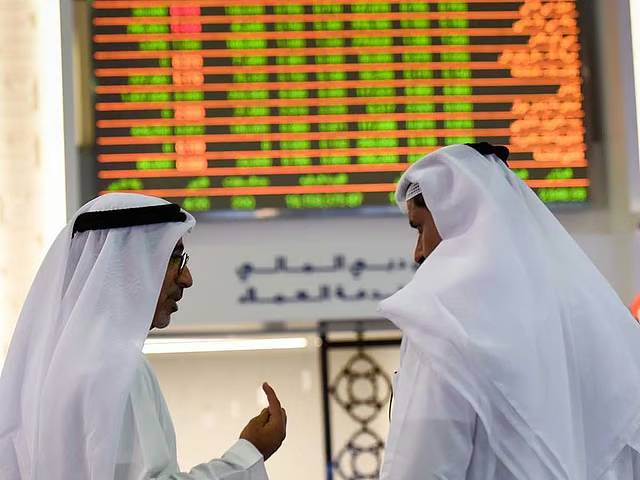
Dubai: The Dubai Financial Market (DFM) surged 3.95 per cent in late trading on Wednesday, marking its biggest single-day gain since April 8. The upward momentum continued on Thursday, with the index trading 0.17 per cent higher at 6,051.23.
The rally lifted DFM’s market capitalisation back above Dh1 trillion, from Dh967.22 billion a day earlier. Abu Dhabi’s exchange also traded in positive territory, reaching a high of 9,572.69 on Wednesday.
Telecoms led sectoral gains, rising 7.81 per cent. Real estate advanced 4.2 per cent, while banking stocks gained 3.99 per cent. Emaar Properties climbed 4.4 per cent and Emaar Development rose 4.89 per cent after Emaar announced a voluntary cash tender offer for up to 100 per cent of its subsidiary.
Big market moves
Asian markets also traded strongly on Thursday. India’s Nifty 50 advanced 1.8 per cent, settling above 24,400, while the Sensex gained 1,550 points. Consumer stocks led the regional rally.
Pakistan’s KSE-100 rose 1.65 per cent, with 383 of the 567 listed stocks advancing during Thursday’s session.
China outperformed other major markets, with the Hang Seng gaining 3.3 per cent and the Hang Seng Tech Index jumping 5 per cent. Tencent and Alibaba each advanced more than 6 per cent, while the Shanghai Composite slipped 0.3 per cent.
Japanese markets moved in different directions. The Nikkei 225 fell 1.6 per cent, while the broader Topix gained 1.3 per cent. Nikkei futures were down 2 per cent.
South Korea recorded the steepest losses, with the Kospi tumbling 5.2 per cent. Samsung Electronics and SK Hynix each shed more than 7 per cent amid concerns over tighter regulations on data centres. Overnight, Nvidia shares also fell 3.17 per cent, trading around the $200 mark.
Tim Waterer, chief market analyst at KCM Trade, warned that the AI data-centre expansion could hit “a regulatory brick wall” if the party follows through on its pre-election pledges.
However, not all market observers share that concern. Ryan Detrick, chief market strategist at Carson Group, noted that buyers were returning following the vote. Many investors see little immediate threat to the broader AI investment theme.
What drove the moves
The US midterm elections triggered a shift away from chipmakers and towards markets that had previously underperformed.
“Greater scrutiny of AI regulation, data centres, energy costs and investment incentives arrives when investors are already questioning the returns on enormous AI spending,” said Charu Chanana, chief investment strategist at Saxo Bank.
She said this could accelerate the shift away from AI-focused investments towards stocks with strong cash flows and pricing power, particularly companies with clear and measurable returns on investment.
Oil prices have also fallen sharply. Brent crude plunged more than 8 per cent on Wednesday before slipping a further 0.7 per cent to $93.94 a barrel. Traders are betting that a Democratic-controlled Congress could accelerate efforts to end the Iran war, now in its ninth month.
US Treasuries rallied for a second consecutive day. The 10-year yield fell by as much as five basis points to 4.84 per cent, its lowest level since September 10. The Bloomberg Dollar Spot Index also slipped 0.2 per cent.
Moves to watch next
Progress on either diplomatic efforts or trade policy could prompt investors to redirect capital towards businesses and regions facing higher import and energy costs.
With bond yields at multi-year highs, debt instruments are becoming more attractive. At the same time, higher refinancing costs could put pressure on companies and weigh on equity valuations. This rotation could change which sectors lead the market without necessarily triggering a sustained, broad-based rally. Funds moving out of technology stocks could lift indices with lower exposure to the sector, although some capital may instead flow into government bonds.
Central banks could add to the pressure. The Reserve Bank of Australia raised its cash rate by 25 basis points to 4.85 per cent on Tuesday. The Bank of England is also expected to announce a 25-basis-point increase on Thursday. Other major central banks have raised rates or signalled tighter monetary policy in the coming months.
However, the election result is not expected to significantly alter the US Federal Reserve’s outlook. According to James Wright, senior trader at Lunaro Financial Services, markets are still pricing in a rate hike in December.
“Slower fiscal spending could ease some price pressure over time. But with CPI inflation at 3.7 per cent, lifted by energy costs and tariffs, Friday’s US payrolls report and the CPI release on November 10 matter far more than the election,” he said.
In the stock market, healthcare and renewable energy shares could benefit from the changing investment landscape. Utilities companies, meanwhile, may face questions over power costs, while banks could see the pace of deregulation slow, Wright observed.